Can You Finance a Bentley Find Out How Much It Really Costs
Can you finance a Bentley? Yes, you can! This guide covers everything about Bentley financing options, including rates, requirements, and hidden costs. Whether you want to lease or buy, you will learn how to secure the best luxury car loan for your dream Bentley.
So you have been dreaming about cruising in a sleek Bentley. The question is, can you finance a Bentley? The short answer is yes. But the full story involves more than just walking into a dealership and signing papers. Financing a luxury car like a Bentley requires planning, research, and a clear understanding of what you are getting into.
This guide breaks down everything you need to know about Bentley financing options. From credit score requirements to hidden ownership costs, we cover it all. By the end, you will know exactly what it takes to bring home a Bentley and keep it on the road.
Key Takeaways
- Financing a Bentley is possible: Multiple lenders and dealers offer luxury car loan options for various credit profiles.
- Bentley financing rates vary: Your credit score, down payment, and model choice all impact your interest rate and monthly payment.
- Leasing offers lower payments: A Bentley lease can reduce your monthly cost compared to a traditional purchase loan.
- Hidden costs add up: Insurance, maintenance, and depreciation are real expenses of Bentley ownership you must plan for.
- Shop around for the best deal: Comparing dealer financing with bank loans can save you thousands over the life of your loan.
📑 Table of Contents
How Bentley Financing Works
Financing a Bentley works much like financing any car, but with higher price tags and stricter requirements. A lender provides you with a loan to cover the purchase price. You then repay that loan over time with interest. The term length, interest rate, and down payment all shape your monthly payment.
Most Bentley dealer financing offers loan terms between 48 and 84 months. Shorter terms mean higher monthly payments but less interest paid overall. Longer terms lower your monthly bill but cost more in the long run. Your Bentley financing rates depend heavily on your financial profile.
Types of Financing Available
You have several paths when exploring luxury vehicle financing. Here are the most common options:
- Dealer financing: The Bentley dealer partners with a lender to offer you a loan directly at the dealership.
- Bank or credit union loan: You secure a loan from your bank before visiting the dealer. This gives you negotiating power.
- Online lenders: Digital lenders often offer competitive rates and fast approval processes.
- Lease financing: Instead of buying, you pay a monthly fee to use the car for a set period.
Each option has pros and cons. Can you finance a Bentley through any of these? Absolutely. The best choice depends on your credit, budget, and how long you plan to keep the car.
Bentley Models and Their Prices
Before you dive into financing, it helps to understand what you are paying for. Bentley offers several models, and their Bentley purchase price varies widely. Here is a quick look at popular models and their starting prices:
Bentley Continental GT
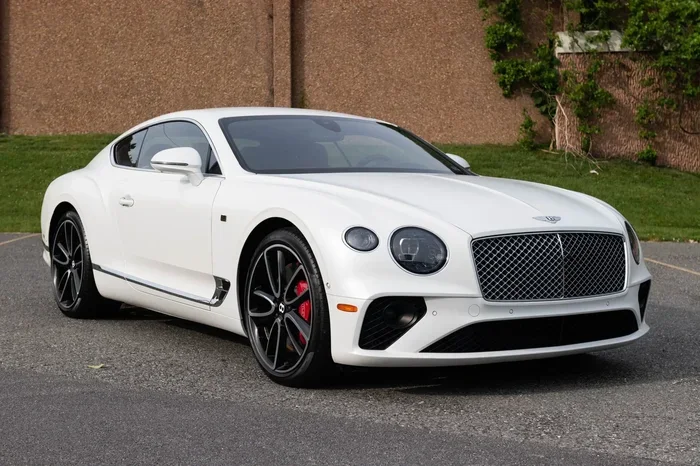
The Continental GT is one of the most sought-after Bentley models. It starts around $230,000 and goes well above $300,000 with options. This grand tourer combines luxury with serious performance, making it a favorite among enthusiasts.
Bentley Flying Spur
The Flying Spur is Bentley’s luxury sedan. It starts around $210,000 and offers a perfect blend of comfort and style. Many buyers choose this model for daily driving with a touch of elegance.
Bentley Bentayga
The Bentayga is Bentley’s luxury SUV. Starting prices hover around $180,000. It delivers spaciousness, power, and the signature Bentley experience in an SUV package.
Bentley Mulliner Models
Bentley’s Mulliner division creates bespoke, ultra-luxury vehicles. Prices for Mulliner models can exceed $400,000 easily. These are custom-built masterpieces for buyers who want something truly unique.
When you can you finance a Bentley, the model you choose directly affects your loan amount. A higher price means a larger loan, which impacts both your monthly payment and the interest you pay over time.
Credit Score and Financing Requirements
Your credit score for luxury car financing matters more than you might think. Lenders view a Bentley purchase as a high-risk loan because of the steep price tag. They want to be confident you can handle the payments.
What Credit Score Do You Need?
Most lenders prefer a credit score of 700 or higher for Bentley financing eligibility. However, some dealers work with scores as low as 620. Keep in mind that lower scores mean higher interest rates, which can add thousands to your total cost.
Here is a simple breakdown of how credit scores affect Bentley financing rates:
- Excellent (750+): You qualify for the best rates, often below 4% APR.
- Good (700-749): Competitive rates, typically between 4% and 6% APR.
- Fair (650-699): Expect rates between 6% and 9% APR.
- Poor (600-649): Rates may exceed 9% APR, and approval is not guaranteed.
Other Requirements
Beyond your credit score, lenders look at your income, debt-to-income ratio, and employment history. Most luxury car loan providers want to see a stable income and a debt-to-income ratio below 40%. You may also need to provide proof of assets or make a substantial down payment.
The Bentley down payment typically ranges from 10% to 20% of the purchase price. On a $250,000 Continental GT, that means putting down $25,000 to $50,000 upfront. A larger down payment lowers your monthly payment and shows lenders you are financially committed.
Leasing vs Buying a Bentley
One of the biggest decisions you will face is whether to lease or buy your Bentley. Both options have distinct advantages, and can you finance a Bentley through either method is a resounding yes.
Leasing a Bentley
Leasing a Bentley means you pay for the vehicle’s depreciation during the lease term, typically 24 to 48 months. Your Bentley lease payments are usually lower than loan payments for the same car.
Benefits of leasing include:
- Lower monthly payments compared to a purchase loan.
- You can drive a new model every few years.
- Warranty coverage often covers most repairs during the lease.
- No hassle of selling the car later.
Drawbacks include mileage limits (usually 10,000 to 15,000 miles per year), wear-and-tear charges, and no ownership equity at the end of the lease.
Buying a Bentley
Buying a Bentley means you own the vehicle outright once the loan is paid off. Your Bentley monthly payment will be higher than a lease payment, but you build equity over time.
Benefits of buying include:
- Full ownership with no mileage restrictions.
- You can customize and modify the car freely.
- Long-term value if you keep the car for years.
- No lease-end fees or restrictions.
Drawbacks include higher monthly payments, full responsibility for maintenance after warranty expires, and potential depreciation in value.
Quick Comparison
Here is a simple side-by-side look at leasing versus buying a Bentley:
- Leasing: Lower monthly cost, no ownership, mileage limits, newer models more often.
- Buying: Higher monthly cost, full ownership, no mileage limits, long-term equity.
Your choice should align with your lifestyle, budget, and how long you plan to keep the car.
Hidden Costs of Bentley Ownership
Financing a Bentley is only part of the equation. The real cost of ownership goes far beyond your monthly payment. Many buyers underestimate what it takes to maintain a luxury vehicle like a Bentley.
Insurance Costs
Bentley insurance cost is significantly higher than for average cars. Luxury vehicles cost more to repair and replace, which drives up premiums. Expect to pay $300 to $600 per month for comprehensive coverage on a Bentley. Your driving record, location, and coverage level all influence the final price.
Maintenance and Repairs
Bentley maintenance cost is another major factor. Routine services like oil changes, brake pads, and tire rotations cost more than on standard vehicles. A full service at a Bentley dealership can easily run $1,000 or more. Major repairs, such as engine or transmission work, can cost several thousand dollars.
Bentley recommends regular maintenance every 6,000 to 10,000 miles. Keeping up with these services protects your investment and prevents costly breakdowns later.
Depreciation
Like all cars, Bentleys lose value over time. However, some models hold their value better than others. The Bentley resale value depends on the model, condition, mileage, and market demand. Popular models like the Continental GT tend to depreciate more slowly than less well-known vehicles.
On average, a Bentley loses about 30% to 40% of its value in the first three years. This means if you buy a $250,000 Bentley, it could be worth $150,000 to $175,000 after three years. Planning for this depreciation helps you make smarter financial decisions.
Fuel and Daily Driving
Bentleys are not known for fuel efficiency. Most models get between 12 and 18 miles per gallon in combined driving. If you drive 1,500 miles per month, you could spend $300 to $500 on fuel alone, depending on gas prices and your driving habits.
Tips to Get the Best Bentley Financing Deal
Now that you understand the costs, let us talk about how to get the best deal on your Bentley financing. A few smart strategies can save you thousands of dollars over the life of your loan.
1. Check Your Credit Before You Visit the Dealer
Know your credit score before you start shopping. This gives you a realistic idea of what rates you qualify for. If your score needs improvement, spend a few months boosting it before applying for Bentley financing. Pay down debts, correct errors on your credit report, and avoid opening new accounts.
2. Get Pre-Approved for a Loan
Securing an auto loan pre-approval from your bank or credit union gives you a strong negotiating position. You walk into the dealership knowing exactly what rate and terms you can get elsewhere. This takes the pressure off the dealer’s financing team and puts leverage in your hands.
3. Negotiate the Total Price, Not the Monthly Payment
Dealers sometimes focus on lowering your monthly payment by extending the loan term. While this sounds appealing, it means you pay more interest over time. Always negotiate the total purchase price first. A lower sticker price directly reduces your loan amount and total interest paid.
4. Compare Multiple Lenders
Do not accept the first financing offer you receive. Compare rates from at least three lenders, including your bank, the dealer, and an online lender. Even a half-percent difference in APR can save you thousands over a five-year loan.
5. Consider a Shorter Loan Term
A 48-month or 60-month loan has higher monthly payments but saves you significant interest compared to a 72-month or 84-month term. If your budget allows, choose the shortest term you can comfortably afford.
6. Make a Larger Down Payment
Putting more money down reduces your loan amount and monthly payment. It also improves your chances of approval and may qualify you for a better interest rate. Aim for at least 20% of the purchase price if possible.
Expert Insight
According to automotive finance experts, the biggest mistake buyers make is focusing only on the monthly payment. The total cost of the loan matters far more. A lower monthly payment spread over 84 months can cost thousands more than a higher payment over 48 months. Always calculate the total interest you will pay before signing any agreement.
Common Mistakes to Avoid When Financing a Bentley
Even experienced car buyers make mistakes when financing a luxury vehicle. Here are some pitfalls to watch out for:
- Skipping the research: Not comparing rates and terms across lenders leaves money on the table.
- Ignoring the total cost: Focusing only on monthly payments can lead to a much more expensive loan overall.
- Underestimating insurance costs: Many first-time Bentley buyers are shocked by their insurance premiums.
- Forgetting about taxes and fees: Sales tax, registration fees, and dealer charges add thousands to your total cost.
- Rolling negative equity into a new loan: If your current car is worth less than what you owe, do not roll that balance into a new Bentley loan.
- Choosing the longest term for lower payments: This strategy costs you the most in interest over time.
Avoiding these mistakes keeps your Bentley financing experience positive and affordable. Take your time, do the math, and never rush into a loan agreement.
Is Financing a Bentley Worth It?
This is the question every potential buyer should ask. Can you finance a Bentley? Yes. But should you? The answer depends on your financial situation and priorities.
If you have a stable income, strong credit, and the budget to handle monthly payments plus ongoing costs, financing a Bentley can be a rewarding experience. Owning a Bentley is about more than transportation. It is a statement, an experience, and a lifestyle choice.
However, if you are stretching your budget thin or have significant debt, a Bentley may not be the right move right now. The costs of ownership extend far beyond the loan payment. Insurance, maintenance, fuel, and depreciation all add up quickly.
The smartest approach is to be realistic about what you can afford. Create a detailed budget that includes all ownership costs. If the numbers work, a Bentley can bring years of enjoyment and pride. If they do not, it is perfectly okay to wait or consider a more affordable luxury option.
Conclusion
Can you finance a Bentley? Absolutely. The path to Bentley ownership is open to buyers with strong credit and solid financial planning. From understanding Bentley financing options to comparing lease and purchase deals, this guide has given you the tools to make an informed decision.
Remember to check your credit score, get pre-approved, and compare multiple lenders before signing anything. Factor in all the hidden costs of ownership, including insurance, maintenance, and depreciation. With the right preparation, you can secure a financing deal that fits your budget and brings you one step closer to owning the luxury car of your dreams.
Take what you have learned here and apply it. Research your options, set a realistic budget, and approach the process with confidence. Your dream Bentley is closer than you think.
Frequently Asked Questions
What credit score do I need to finance a Bentley?
Most lenders prefer a credit score of 700 or higher for Bentley financing. Some dealers may work with scores as low as 620, but you will likely face higher interest rates. The higher your score, the better your financing terms will be.
How much of a down payment do I need for a Bentley?
A typical down payment ranges from 10% to 20% of the purchase price. On a $250,000 Bentley, that means $25,000 to $50,000 upfront. A larger down payment reduces your monthly payment and may help you qualify for a lower interest rate.
Is it better to lease or buy a Bentley?
It depends on your lifestyle and goals. Leasing offers lower monthly payments and lets you drive a new model every few years. Buying gives you full ownership and no mileage restrictions. Choose the option that fits your budget and how long you want to keep the car.
What are the monthly costs of owning a Bentley?
Beyond your loan payment, expect to pay $300 to $600 per month for insurance, $100 to $200 for fuel, and several hundred dollars for routine maintenance. The total monthly cost of Bentley ownership can easily exceed $1,000 depending on the model and your usage.
Can I get a Bentley loan with bad credit?
Getting approved for Bentley financing with bad credit is challenging but not impossible. Some subprime lenders specialize in luxury car loans for lower credit scores. However, expect significantly higher interest rates and stricter loan terms. It may be better to improve your credit before applying.
How long does Bentley financing approval take?
Most lenders provide a decision within 24 to 72 hours. Dealer financing can sometimes be approved on the same day. Having all your financial documents ready speeds up the process significantly. Pre-approval from your bank can also streamline the timeline.